February 21, 2012

The best bank regulator knows absolutely everything about banking… or nothing at all.

Sir, Patrick Jenkins, in “Bank of England needs more than a new governor”, February 21, comments on how much a governor might need to know about banking in order to understand the banks it will soon have to regulate. My answer is either all or nothing at all. Let me explain. 

If bankers knew what they were up to and their risk perceptions and risk models were perfect, then there would be no problems. Therefore the regulators should never ever bet the house on the bankers being correct, as they currently do with their capital requirements for banks based on perceived risk, but always prepare for the consequences of the bankers being wrong. 

And those best positioned to do so are either the ones who know absolutely nothing of the risk perceptions and risk models, and therefore do not want to have anything to do with these, or those who know everything about risk perceptions and risk models, and therefore also do not want to have anything to do with these. 

The truly dangerous ones are those who know a little about risk perceptions and risk models but who do not want to admit to any ignorance. In other words the truly dangerous bank regulators are precisely those we have.

February 18, 2012

Naïve trust was what caused Greece’s illness.

Sir, Tony Barber titles his article “Malignant mistrust threatens to be the death of Greece” February 18 and speaks about “the slow uncoiling of malignant forms of mistrust in Greek society”. 

Hello, where has Mr. Barber been! I have never ever known a Greek who has expressed trust in his government, has he?, and, if something really caused the death of Greece, that was the bank regulators’ incredibly naïve trust in Greece which they shown by allowing all European banks to lend to its government holding only 1.6 percent in capital. 

The Greeks meanwhile, knowing the Greeks never thought of doing something as stupid as lending to their government so much money at so low rates, and so instead they took a couple of hundred of billions Euro out of Greece and lend it among others to the German Government. 

And so now we have for instance German banks with billions of Greek debt, and Greek citizens with billions of investments in German debt which sort of leads us to the question of… who seem to be better off? 

The reason the Greece problem has not been solved, is not because Greece can’t pay, everyone knows that, it is because Europe is left holding the bag.

February 16, 2012

Who’s really shortchanging who in India?

Sir, David Pilling in “India’s ‘bumble bee’ defies gravity”, February 16, writes: “By selling the licences on the cheap, the telecom ministry is accused of shortchanging the exchequer to the tune of $39bn.” 

Indeed, but, one could just as well argue that if selling the licenses for $39bn more, the exchequer would then be shortchanging the mobile telephone users, to the tune of $39bn plus expected returns more in fees, and over a very long time. 

In other words the $39bn are equal to taxes collected in advance,to be paid by users that are not even aware of it, meaning something which is not an example of transparency. 

In other words the $39bn will have to be repaid at the rate of return required by the telecom investor, rather than at the usually lower interest paid by the government on its public debt, meaning something which is not an example of economic rationality.

February 15, 2012

The first lesson from Greece for the eurozone… the existence of loony bank regulators!

Sir, Martin Wolf asks “What does Greece…this small, economically weak and chronically mismanaged country…tell us about the eurozone?”, “Much too much ado about Greece”, February 15. 

Well, the first thing it clearly tell us, is that the eurozone banks have been in the hands of loony regulators… who allowed the eurozone banks to leverage with Greek public debt 62.5 to 1. Without it, Greece would not have been able to ramp up as much debt, no matter how bad and fraudulent its accounting. 

And the second thing it tells us, is that the accountability and good-governance within the eurozone is basically non-existent. It is basically the same regulators who produced the failed Basel II, which are now in charge of producing Basel III with only minor changes in the script, except of course for those regulators that have been promoted. There has not even been the slightest hint of the bank regulators having been Sarbanes-Oxleyed. 

PS. Europe, if doctors can be sued for malpractice, why can’t bank regulators?

February 14, 2012

There´s no reason for any risk-weighting of bank assets, after risk-adjustment has already taken place in the price and terms of these

Sir, Brooke Masters, your Chief Regulation Correspondent writes: “capping total leverage has a disproportionate impact on banks that provide basic services to the wider economy such as financing overseas trade. Because these are low-risk activities, they require very little capital under the risk-weighted-assets system, but under the leverage ratio they are treated exactly the same as high-risk derivatives and speculative loans.”, “Leverage ratio has the power to help banking tree thrive” February 14. Let me make the following comments. 

First, and as this crisis has so clearly proven, let us be crystal clear on the fact that “they require very little capital” does not by any means turn these into “low-risk activities”. 

Second, in terms of capital requirements, what is wrong with “low-risk activities” being treated “exactly the same as high-risk derivatives and speculative loans”? Have not the banks already cleared for differences in perceived risk by means of different interest rates, amounts exposed and other terms? It is precisely the double dipping into perceived risks, that have saddled our banks with excessive exposures to what is has officially been perceived as not-risky and created equally dangerous underexposures, like for instance in lending to small businesses and entrepreneurs, only because the latter have officially been deemed more risky by some wimpy bureaucrats. 

Basel Committee, please stop infantilizing our banks!

February 11, 2012

Greece’s infantilization is nothing when compared to that of our banks.

Sir, you write that the eurozone’s approach to help Greece has been to infantilize it, “Let Greece stand on its own feet”, February 11. This is absolutely correct and very worrisome but, why do you in FT insist on ignoring the much more tragic and serious infantilization of our whole banking system? 

In essence by means of the interest rate and the size of the exposure, grown up bankers should be able to act on what they perceive as the risk of default of borrowers without any interference. But, the regulators, in a sublime nanny-like effort to keep the banks out of trouble, imposed capital requirements which allow the banks to hold much less capital when the perceived risk are low than when these are high. 

As a direct result, we now have our banks drowning in dangerous excessive exposures to what was perceived as not-risky, like triple-A rated securities and infallible sovereigns (like Greece); and maintaining equally dangerous underexposure to what is perceived as risky, like in lending to small businesses and entrepreneurs. 

A Western world which has prospered because of its willingness to take risks is now shivering in fright and huddling taking refuge in whatever safe-ports are left… and these safe-ports are of course becoming more and more dangerously overcrowded.

FT wake up!

February 08, 2012

India, whatever you do, do not forget that risk-taking, not risk-aversion, is the oxygen of development.

Sir, Martin Wolf in “Crisis must not change India’s course”, February 8, would perhaps like to make clear to his green readers that when he writes “India can generate rapid growth by catching up on the world’s richest countries, almost regardless of the global environment” that it was not that “global environment” he was referring to. 

Wolf then recommends carefully watching the financial system and adopting the emerging global norms, because “Huge crisis may be socially manageable for high-income countries. They would be grossly irresponsible for a country like India”. I completely disagree. 

Global banking norms, which have emerged in the developed world, are designed to encourage banks to invest in what is not risky, completely ignoring the efficient capital allocation purposes of a bank, and that, though sad and not good, might be something acceptable for a high-income country that wants to hold on to what it’s got, is completely unacceptable for a poor developing country. 

A country like India cannot afford to forget that the cost of keeping its banks safe could be much larger than a bank crisis, because of all the developing opportunities foregone. Someone ought to have asked Mr. Wolf how his country developed and what banking norms were in place in his country before the current ones.

February 07, 2012

What is most appropriate, cones of shame or tarring and feathering?

Sir, in “Banks at risk” February 7, notwithstanding that you, at long last, write about the incestuous relations of banks with national government and admit that many countries see banking as an extension of the state, you mention only the taxpayers subsidies to banks, but ignore the immense subsidies governments collect, in terms of more public debt and at lower interest rates that what a free market would allow, as a result of being able to borrow from banks without generating, when compared to other borrowers, as much capital requirement. 

Current bank regulations, produced by our banking central planners, decided that the only thing that matters is that banks do not default, and this set our banks on the course of creating huge excessive exposures to what is officially deemed not risky, and to equally dangerous underexposures to what is deemed as risky. 

That our banks are now at risk? Ha! The whole Western world is at risk 

How are these regulators now best shamed, having them parade down Trafalgar Square wearing cones of shame, or would tarring and feathering be more appropriate.

February 04, 2012

We should also strip the Financial Times of its honorable motto

Stripping someone of his honorific title does seem to be a quite civilized way to shame those who seemingly have done society wrong… and society really needs to recover, urgently, some serious shaming powers. 

That said, in order for shaming to really work, it should not be seen as singling out someone to shame, like in the case of Fred Goodwin, especially when it is well known that others should be on the list.

Independently of what regulators say, the banks and the markets consider the perceived risk of default, such as that information contained in the credit ratings, when it sets the interest rates, the amounts and the other terms of a financial exposure. 

That is why, when the regulators decided to use the same information for setting the capital requirements for banks, they guaranteed an excessive bank exposure to what is officially perceived ex-ante as not risky, like the triple-A rated securities and infallible sovereigns, and an underexposure to what is officially perceived as risky, like lending to small businesses and entrepreneurs… and that was the primary cause of this systemic financial and bank crisis.

I have written literarily hundreds of letters to the Financial Times during the last seven years about this almost unbelievable mistake committed by the bank regulators, and these have all been ignored. Now, if truth is silenced, we should not be surprised to see many pseudo-truths prosper, which is one reason that banker bashing has achieved its current levels of popularity and why regulators have not even come close to being held to any real account.

Therefore I am of course in total agreement with Martin Dickson´s “The burn-a-banker frenzy is tempting – but wrong”, February 4, when he reminds us of perhaps also burning “those meant to police the credit system”. 

But, to that, I would also add the need of stripping the Financial Times of its honorable motto “Without fear and without favour”, since obviously its silence, can only be explained in terms of journalistic or media cronyism... which is a public bad.

February 02, 2012

Let us hope we are not ordered to do or not to do something because of long term central-bank projections.

Sir, Charles Goodhart in “Longer-term central bank forecasts are a step backwards” February 2, writes: “If official predictions contain additional information beyond that implied by market forecasts of the term structure of short-term interest rates then well and good. If not, then all central bankers are doing is exposing that they are as clueless about the future as the rest of us.” 

That is correct, but at least a long-term central bank forecasts is, for now, not being pushed down the throat of a market which has already considered that information, like happens when the bank regulators, with their capital requirements based on perceived risk, and as primarily perceived by their outsourced official risk perceivers, the credit rating agencies, push that information again down the throats of the banks. 

But, who knows, any moment, someone could order us to do or not to do something based on those long-term central bank forecasts.

A market distortion error is much worse than a model error

Sir, as you might guess from my hundreds of letters to you over the last 5 years and which were ignored, I completely agree with Pro Johan Lybeck that we should “Forget Basel III and head straight for Basel IV” February 2. I have though two differences with him. 

When he suggests “fixed risk-weight for all assets, so as to eliminate “model error”, I much prefer the same risk-weight for all assets, so as to eliminate the much worse non-transparent market distortion error. 

The second difference is that he suggests that the changes in capital requirements should be implemented now, even though that could mean banks could be partially owned by the state because they cannot raise new capital in time. My suggestion is to allow banks to keep the original capital requirements on any assets booked previously, since there is no need to cry over spilled milk, and allow the banks to use whatever new capital they can raise for the new business we so sorely need.

February 01, 2012

Martin Wolf, it is the risk-taking austerity we’ve really got to be scared of

Sir, Martin Wolf writes that “Europe is stuck on life support” February 1, and concludes that only shifts in competitiveness between the members will give the latter the opportunity to survive disconnected. Who would not agree, the issue is how to achieve that. It starts by better understanding what caused this mess we’re in and, in that debate, much more important than discussing the dangers of fiscal austerity, is realizing the dangers of risk-taking austerity.

The banks, courtesy of the Basel regulations and the capital requirements based on perceived risk, have now all been painted into the corner of what is officially perceived as not-risky, and where of course any real shifts in competitiveness do not normally reside.

Take for instance Italy, in many ways it has survived in spite of its governments, and, nonetheless any European bank is currently required to have much more capital when lending to an Italian small businesses or entrepreneur than when lending to the Sovereign Italy.

Mr. Wolf, at this moment, much more than a Heinrich Brüning, who we really must fear, are the sissies in the Basel Committee, in the Financial Stability Board and in the UK’s own FSA.

January 31, 2012

How come the real flaw of Basel bank regulations is not even discussed?

Sir, Karel Lannoo, in “Rulemakers in Europe must flex muscles on Basel III”, January 31, gives a good description of many of the particular problems derived from the current capital requirements for banks, but is yet incapable of pinpointing the true core of what´s wrong with these… namely that regulators add their risk discrimination on top of the risk discrimination that already occurs in the market. But, of course, it is not only Mr. Lannoo, who fails to see that.

Recently John Reed, a former Chairman and CEO of Citicorp, a former Chairman of the New York Stock Exchange and currently the Chairman of the Massachusetts Institute of Technology's Office of Corporation, during an interview in a program of Bill Moyer titled “How Big Banks are rewriting the rules of our economy” said the following:

“It does not take a genius to see what happened … the presumption that you can capture risk by looking at historical volatility…. As soon as you say something appears not to be risky you get an overinvestment in it because the capital requirements are less, and then if something does go wrong the hurt is all the more because you do not have the capital to cover that risk”

But what does obviously not take a genius to see, even I saw it, and about which I have written hundreds of letter to FT, is something still totally ignored in the debate, and in the rewriting of the next Basel version. The useless and so dangerous capital requirements for banks based on perceived risks remain the main pillar of the Basel bank regulations. How come?

Ref: 17:40 to 18:15

January 26, 2012

Big time meddler Greenspan is no one to warn us about meddling with the market.

Sir, Alan Greenspan is one of those responsible for the regulations which require banks to hold quite a lot of capital when lending to small businesses and entrepreneurs but allow these to lend to the government against no capital at all. As such he is de-facto one of the biggest market meddlers of our time, and has no moral right to appear in the Financial Times preaching us with “Meddle with the market at your peril” January 26. 

As former chairman of the US Federal Reserve he must be aware that the whole world economy is flying blind, because of those capital requirements… like what would the rate on US treasury be if the banks had to treat citizens and government alike?

January 25, 2012

Crony journalism is also a public bad

Sir, in “The world’s hunger for public goods”, January 25, Martin Wolf holds that extreme financial instability is a public bad; and which presumably has to mean that correctly understanding the reason for it, should be a public good. 

Nonetheless, over many years now, the explanation that I give for the current crisis, as an individual who provided some of the clear and earliest documented warnings, even in FT, and which I thought I could make public through sending letters to FT, has been silenced. For what reasons, I do not know… but it could perhaps be explained in terms of crony journalism. 

Nonetheless, here is an explanation again, for the umpteenth time. 

If a banker after analyzing a borrower’s creditworthiness decides to limit the amount of the loan, and charge higher interests to compensate for the perceived risks, the borrower might try to renegotiate better terms, but he would not consider it unfair, as it would be the result of natural market discrimination. 

But, when bank regulators also force the bankers to further limit their loan to the borrower, and increase even more the interest rate charged, all because they require the bank to hold more capital when the officially perceived risks are higher than when they are low, as they do, then we enter into the world of the nannies, the world of artificial regulatory risk discrimination; which only leads to the kind of unfairness that exasperates the inequalities. 

As a result of this regulatory risk discrimination we now have a crisis of financial instability that threatens to take the Western world down; all because of excessive bank exposures to what is officially perceived ex-ante as not risky – for instance, triple-A rated mortgage-backed securities or “infallible” sovereigns and a growing bank underexposure to what is officially perceived as risky – for instance, lending to small businesses and entrepreneurs. 

The parents need to discuss this issue urgently with their financial nannies, before it is too late and the economy has turned terminally sissy and terminally unfair. 

PS. Occupy Basel! http://bit.ly/dFRiMs

We are living dangerously in the land of officially declared safeness!

Sir Martin Wolf’s “Yet another year of living dangerously” January 25 would have benefited from the subtitle “in the land of perceived safeness”. The world has in fact been living extremely dangerous, ever since the Basel II rules were approved in June 2004, and which set of a frantic race for whatever assets were officially perceived as not risky and that, just because of that, required the banks to hold extremely little capital. 

Much of the global macroeconomic imbalances that Mr. Wolf obsessively insist on blaming for this crisis, were precisely financed by the fact that banks could lend or invest trillions against only 1.6 percent in capital or even less. 

To save the world from the current dangers, we need to get rid of the nannies in Basel and help our bankers relearn how to take real bank risks and not just regulatory arbitrage risks. 

January 23, 2012

For fixing finance, start by getting rid of the official risk-weights

Sir, when on markets´ and bankers´ natural risk adverseness, you stack on regulators´ risk adverseness, applying Basel risk-weights, you get too much risk adverseness, which naturally results in excessive exposures to what is perceived as not risky and equally dangerous underexposures to what is perceived as risky… precisely what has caused the current crisis. This is what unfortunately Mr. Martin Wolf cannot or does not want to understand.

When in “Seven ways to fix the system´s flaws”, January 23, Mr. Wolf calls for more bank capital, suggesting a leverage of ten to 1, he just ignores the fact that the higher the capital requirements, the larger will be the distortions produced by the perceived risk discrimination that result from the use of official risk-weights.

January 20, 2012

Don’t downgrade the rating agencies, downgrade the regulators.

Sir, already a couple of years into this crisis Philip Stephen shows a surprising lack of understanding of it, in his “Downgrade the rating agencies”, January 20. 

Suppose that human fallible credit rating agencies were able to produce absolutely perfect ratings, in terms of measuring the risk of default, and which are of course used by the banks to choose who to lend to, how much, and at what rate. 

But consider the fact that regulators imposed capital requirements for banks that were also based on the same ratings, and which functioned therefore like a hallucinogen, a veritable LSD; increasing the banker’s sensitivity to risk, so that he perceived a good ratings in a much brighter light, and a not so good ratings took on an even scarier appearance. 

As should have been expected by any independent regulator, not part of a incestuous group-think, the consequences were: 

A growing excessive bank exposures to what is officially perceived ex-ante as not risky, like the triple-A rated securities and infallible sovereigns, leading to a dangerous overcrowding of the safe-havens and; 

A growing bank underexposure to what is officially perceived as risky, like in lending to small businesses and entrepreneurs, equally dangerous, because of the lost opportunities to create the next generation of jobs for our grandchildren. 

So again it was not primarily the rating-message’s fault it was the fault of those who ordered how those rating-messages were to be read. Downgrade those regulators! 

Occupy Basel! http://bit.ly/dFRiMs

January 11, 2012

We do not need banks avoiding risks we need banks taking the right risks.

Sir, Vikram Pandit in his comment on “Capitalism in crisis” January 11 rightly refers to the capital requirements for banks set by the regulators based on perceived risk of default as a (arrogant) presumption of “clairvoyance no regulator can posses”. I totally agree with that, but then he suggests bettering the system by having the banks comparing the risk profile of their assets with some “benchmark” portfolio created by the regulators. 

Ha! What would have happened in the building up of the current crisis? Those banks that had held the most of ex-ante triple-A rated securities and of infallible sovereigns would have certainly compared great against the benchmark, and be rewarded for that, but could then have been among those who turned into the worst nutcases when the ex-post realities set in. 

And, if the banks already now shy away way too much from taking on the real risky but rewarding prospects we need them to take, such as lending to the small businesses and entrepreneurs, they would do more so, if subject to a new sort of “neutral” measurement tool. 

Mr. Pandit and Mr. Regulator, we know you are looking to the safety of the banks, but, we other humans need to look at the safety of our economy and the prospects of creating jobs for our grandchildren, and neither capital requirements based on perceived risk nor a “benchmark” portfolio has anything to do with that… on the contrary these just make our prospects so much dimmer.

January 09, 2012

Capitalism is in crisis, being attacked by regulators!

So capitalism is in crisis? Analysis, January 9. Would golf not be in crisis too if the handicap officers assigned more strokes to the good players than to the bad? Would horseracing not disappear if the bad horses had to carry more weight than the good? What would you say about a government that on top of the higher premiums the unhealthy pay, proposes to also tax them because they are riskier? 

The banks are of vital importance for how capitalism functions, and Mark Twain reminded us with his the lending of an umbrella when the sun shines and taking it back when it rains, that bankers might be too risk-adverse. If they were that before, well now they are that a hundred times more. 

Because now, thanks to our ingenious bank regulators, for a bank to finance 100 dollars of what is officially perceived ex-ante as risky, it needs about 8 dollars in capital, but, to finance100 dollars of what is officially perceived ex-ante as not risky, it needs only about 1.6 dollars. 

Which means that when a bank lends to what is officially perceived ex-ante as risky, it can earn the risk and cost adjusted margins of those loans about 12 times for each dollar of bank capital, but, when lending to what is officially perceived ex-ante as not risky, it can earn the risk and cost adjusted margin of those loans more than 60 times for each dollar of bank capital. 

The natural consequence of such stupidity, is that the lending to what ex-ante is officially perceived as risky, like the lending to entrepreneurs and small businesses, is in relative terms made much less interesting for the banks, while the lending to what ex-ante is officially perceived as not risky, like the triple-A rated and infallible sovereigns, is given extraordinary incentives. 

And so the perhaps most important and dynamic participants of capitalism, the small businesses and entrepreneurs, are either not getting bank loans, or having to pay much more for these, all while, what is ex-ante officially perceived as absolutely safe-havens, and therefore already easily attracted cheap funds, are now, ex-post, turning into dangerously overcrowded havens. 

A byproduct of such stupidity is of course also that an allowed bank leverage of more than 60 times, serves as the most potent growth-hormone for the too-big-to-fail banks and of the too-big-to be-decent banker bonuses. 

What to do? Let capitalism be capitalism. Capitalism discriminates sufficiently on its own based on ex-ante perceived risks, so as to need further assistance from the excessively worried nannies in the Basel Committee for Banking Supervision.

More of this in the video

December 29, 2011

Has FT just turned into an Occupy Wall-Street extremist?

Or are you just expressing pent-up jealousy about banker’s bonuses? 

In “Restoring faith in the banking system” December 29 you write “Prior to the crisis, bankers garnered great fortunes by loading individuals and companies with excessive and unnecessary debt, or by churning investment portfolios to extract transaction fees.” Frankly, what on earth does that have to do with causing the current crisis? 

We are not in a mess because of the banker having made to much money on that! We are in a mess exclusively because the bankers built up excessive exposures to what was ex-ante officially perceived as not risky, like triple-A rated securities and “infallible” sovereigns; and that happened exclusively because silly regulators allowed the banks to do so against very little or no bank capital at all. If you want to search for the source of income which originated immense bankers’ bonuses, then look no further than to the outrageous leverages allowed for some assets. 

How on earth will the Western World be able to restore its faith in the banking system with editorials like this which seem to indicate that our only possibility is to sit down and wait for the new good bankers?… like waiting for a New Soviet Man. 

Want to restore faith in the banking system? Throw out those who produced Basel I and II, instead of allowing them to concoct an even more dangerous Basel III. 

PS. You write “The asymmetry of risk and rewards in banks has led to poor outcomes for society” and I must ask, what about the information asymmetry powers you exercise in favor of the opinions of those you want to favor? Do we have to occupy FT too? 

December 21, 2011

US, and the Western World, is becoming “the home of the risk-adverse”.

Sir, I, as most humans, am extremely risk-adverse, and that is why I have always appreciated the role of designated risk-takers that the banks perform for the society. We cowards were used to worry our bankers were too cowards to, with their lending of the umbrella while the sun shines and taking it away when it rains. But then came the bank regulators and with their capital requirements that discriminate fiercely based on perceived risks made it all so much worse. 

Martin Wolf comments on the “Great Stagnation” by Tyler Cowen of George Mason University, December 21. What they both fail to identify is that requiring banks to have a lot of capital when the perceived risks are high, and allowing them to hold minuscule capital when the perceived risks are low, stacks the returns on bank equity against what is perceived as risky. And that has nothing whatsoever to do with what made “the Home of the brave” big. The US is now, as is most of the Western World, becoming the Home of the risk-adverse. 

Not taking risks is about the most dangerous things a society can do… as the only thing that can result from that is the overcrowding of the ex-ante safe-havens

December 13, 2011

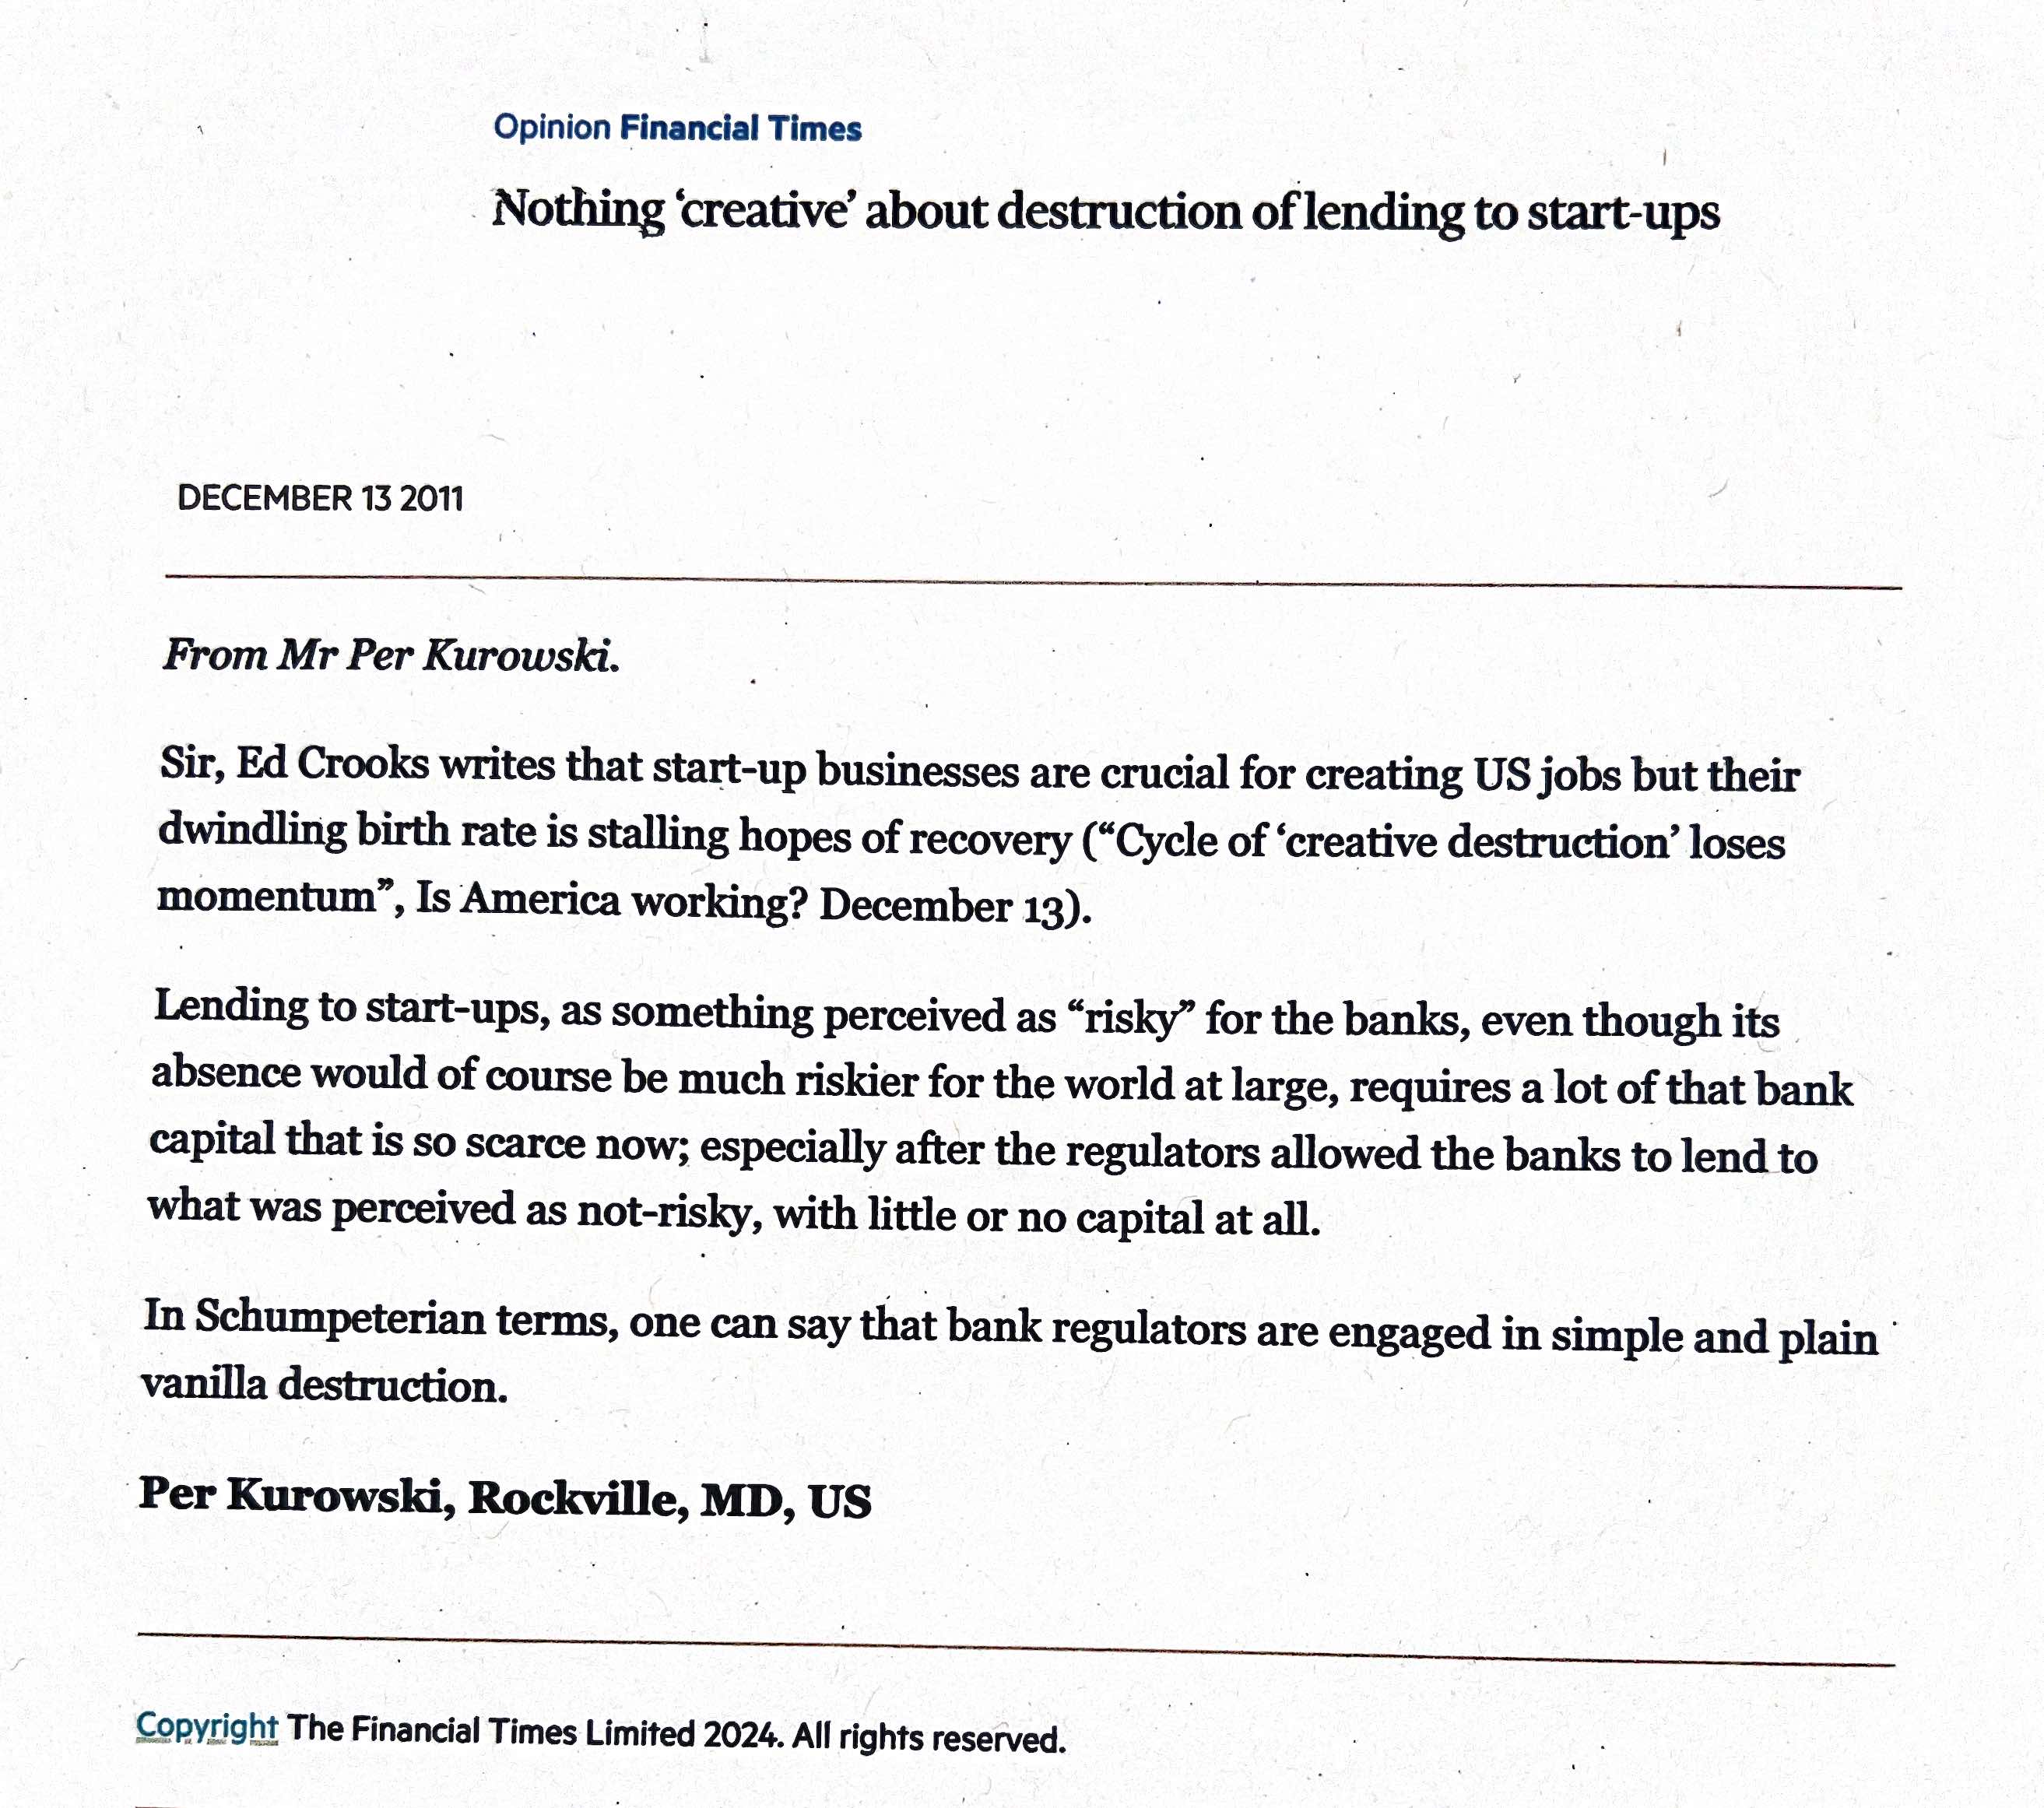
Nothing ‘creative’ about destruction of lending to start-ups

Published in FT, December 14, 2011

Sir, Ed Crooks writes that start-up businesses are crucial for creating US jobs but their dwindling birth rate is stalling hopes of recovery "Cycle of 'creative destruction' loses momentum to start-ups", Is America working? December 13).

Lending to start-ups, as something perceived as “risky” for the banks, even though its absence would of course be much riskier for the world at large, requires a lot of that bank capital that is so scarce now; especially after the regulators allowed the banks to lend to what was perceived as not-risky, with little or no capital at all.

In Schumpeterian terms, one can say that bank regulators are engaged in simple and plain vanilla destruction.


December 12, 2011

The Western World is in a freefall, and no one is discussing the reason why

Simplified, if the cost of funds for a German bank was 2 percent; if it wanted to earn a 1.5 percent margin; if the cost of analyzing the credit worthiness of a German small business was 1 percent; and if the risk that the borrower would default was perceived as 3 percent, then the German bank would charge the German small business an interest of 7.5 percent. 

And if the cost of funds for a German bank was the same 2 percent; if it wanted to earn the same 1.5 percent margin; if the cost of analyzing the credit worthiness of Greece was zero, because that is paid by Greece to the credit rating agencies to do; and if the risk that Greece would default was perceived as 1 percent, then the German bank would charge Greece an interest of 4.5 percent. 

If the German bank was required to have about 8 percent in capital against any loan, and could therefore leverage its capital about 12 times, the bank could expect to earn 18 percent on its capital when lending to a German small business or when lending to Greece. 

But that was before the bank regulators of the Basel Committee intervened and messed it all up. 

These regulators, ignoring the empirical evidence that bank crisis never occur because of excessive exposures to what was considered risky but only because of excessive exposures to what was considered as absolutely not risky, with their Basel II, told the banks “You German bank, if you lend to a “risky” German small business you need 8 percent in capital, but if you lend to an infallible Greece you only need to have 1.6 percent in capital”. 

And because that 1.6 percent allowed for a leverage of more than 60 times when lending to Greece, the German bank, though it still could earn a decent 18 percent on its capital when lending to a German small business, suddenly could expect to earn 90 percent on its capital when lending to Greece. Hell, the German Bank could even afford to lower the interest rate it charged Greece and still earn more when lending to Greece than when lending to a German small business. 

And of course the German bank, as did all banks in the Western world, started running to the officially perceived safe-havens of Greece, Italy, Spain, triple-A rated securities and others, where they could earn much more; and of course the governments of the safe havens could not resist the temptations of cheap and abundant loans, and all these safe-havens became dangerously overcrowded… while the small German business found it harder and much more expensive to access any bank credit… and while the too big to fail banks grew even bigger.

And, many years into a crisis that has the Western World in a freefall, this issue is not even discussed, and the same failed bank regulators are allowed to work on Basel III, using the same failed loony and distorting ex-ante perceived risk of default based capital requirement discrimination principle.

Hell, even the Financial Times has decided to ignore the hundreds of letter I sent them about it, and this even when they know they published two letters of mine that clearly warned about what was going to happen. In January 2003, “Everyone knows that, sooner or later, the ratings issued by the credit agencies are just a new breed of systemic errors, about to be propagated at modern speeds” and, in October 2004, “Our bank supervisors in Basel are unwittingly controlling the capital flows in the world. How many Basel propositions it will take before they start realizing the damage they are doing by favoring so much bank lending to the public sector (sovereigns)? 

Occupy Wall Street? No! Occupy Basel! (Perhaps occupy the Financial Times too!)


PS. This post was made before I realized that the reality was even so much worse because, instead of applying to Greece the 20% risk weights Basel II would have ordered EU authorities assigned Greece a 0% risk weights and so European banks, when lending to Greece did not have to hold any capital. How crazy is that?

PS. At the end of the day the EU authorities kept total silence about their mistake and blamed Greece for it all. No solidarity. What a Banana European Union.

December 07, 2011

The blame lies squarely with the regulators not with the credit rating agencies

Sir, Quentin Peel in “Agency’s debt warning provokes angry response” December 7, reports that Christian Noyer the president of Banque de France held that “the rating agencies were one of the motors of the crisis in 2008. 

Mr. Moyer should know better, the motor of the crisis, were the ridiculous low capital requirements for banks allowed by his regulating colleagues in the Basel Committee based on the credit ratings, as if these were infallible and as if doing so would not incentivize the growth of dangerous exposures to what was ex-ante perceived as not risky. 

In January 2003, while being an Executive Director of the World Bank, the Financial Times published a letter where I wrote: “Everyone knows that, sooner or later, the ratings issued by the credit agencies are just a new breed of systemic errors, about to be propagated at modern speeds”. But it looks like Mr. Noyer and his colleagues did not know that!

December 05, 2011

We were thrown back into the Dark Age... by the Basel Committee

Sir, Tony Jackson’s “Why talk of a coming Dark Age is a touch overdone”, December 5, reminded me of Peter L. Bernstein who in Against the Gods (John Wiley & Sons, 1996) wrote that the boundary between the modern times and the past is the mastery of risk, since for those who believe that everything was in God’s hands, risk management, probability, and statistics, must have seemed quite irrelevant. 

Ironically, we might now be thrown back into the Dark Ages, because of bank regulators who thought themselves Gods, and assigned minimal or even zero percent risk weights, those used when determining the capital requirements for banks, to what they thought were the infallible, the triple-A rated and the solid sovereigns.

Europe, the Basel Committee should and needs to be blamed for the crisis.

Sir, Wolfgang Münchau goes to the core of the European issue when he writes that its leaders’ narrative, which reduces the crisis to a failure of fiscal discipline, is probably the underlying reason why all their crisis resolutions efforts have failed so far”, “France and Germany look set to fudge it yet again”, December 5.

Indeed, had the European leaders understood two letters that I wrote and were published by FT, the narrative would be quite different, in fact Europe could perhaps not even be facing this crisis.

The first letter, January 2003 said “Everyone knows that, sooner or later, the ratings issued by the credit agencies are just a new breed of systemic errors, about to be propagated at modern speeds”. The second, October 2004, “Our bank supervisors in Basel are unwittingly controlling the capital flows in the world. How many Basel propositions it will take before they start realizing the damage they are doing by favoring so much bank lending to the public sector [sovereigns]?

From the content of those two letters it is easy to understand that no matter what intrinsic and real problems the eurozone has and no matter the natural fiscal indiscipline of politicians in general, Europe would not have faced this crisis had the bank regulators in Basel known better.

December 02, 2011

Small and frequent tremors might help to keep the big one away.

Sir, Roger Altman concludes “We need not fret over the omnipotent markets” December 2, with “There may be more frequent market crisis. We should not rush to conclude that they will end in tears”. I would word it differently, the more frequent the market crisis, the less the probability it will end in tears. 

In May 2003, as an Executive Director of the World Bank (just 1 of 24) I made the following comment at a workshop for bank regulators at the World Bank: “A regulation that regulates less, but is more active and trigger-happy, and treats a bank failure as something normal, as it should be, could be a much more effective regulation. The avoidance of a crisis, by any means, might strangely lead us to the one and only bank, therefore setting us up for the mother of all moral hazards—just to proceed later to the mother of all bank crises. Knowing that “the larger they are, the harder they fall,” if I were regulator, I would be thinking about a progressive tax on size” 

In my country, Venezuela, when it trembles just a little, many of us applaud, because we feel that small tremors might help to keep the huge ones away.

December 01, 2011

Right or wrong should not be a calculated risk.

Sir, John Gapper should be congratulated for clearly opining that “Judge Rakoff is just doing his job”, December 1. Judicial deal makings, aka settlements, introduce risk calculations in matters of what is right and what is wrong, that can rot even the strongest society. 

I just wish there would also be a Judge Rakoff out there who would be willing to question the right of the regulators to place a layer of arbitrary discrimination of those perceived as “risky”, on top of the natural market discrimination that already exist against them. In other words, what constitutional right do regulators have to decide that a bank needs to hold substantial capital when lending to a citizen, but needs no capital at all when lending to an infallible sovereign?

November 30, 2011

What the IMF should tell the Basel Committee

Sir, Martin Wolf in “What the IMF should tell Europe” November 30, writes “Fiscal indiscipline did not cause this crisis. Financial and broader private sector indiscipline, including by lenders in the core countries, was even more important.” Again, Martin Wolf refuses to acknowledge that most of that “indiscipline” was caused by the incestuous group-think that afflicted bank regulators and made them come up with truly senseless regulations. He should consider that his call for “ruthless truth-telling” applies to him too. 

What I would urge the IMF to use its portent voice for at this moment is to instead of advising Europe advising the Basel Committee, telling it:

"You allowed the banks to lend to ´infallible sovereigns´ and ´super-safe´ triple-A rated privates with little or no capital at all, and, as a result, the monstrous exposures that turned safe-havens into dangerously overcrowded havens were generated... But now is not the moment to make up for all the capital that should have been in place when banks booked their assets, not when the risks were discovered… and so allow all the banks to keep their current exposures backed with whatever bank capital was originally required from them… so to permit that all new bank capital is not to fill holes but can be used to back new operations… but which all have to meet the same basic capital standard no matter what the ex-ante perceived risk is.”

November 15, 2011

Baloney Mr. Chan! What the Western World most needs is to free their banks of their stupid regulations.

Sir, I know that the current crisis, and that has until now mostly affected the Western World, was primarily caused by the bank regulators who innocently thought they were doing us a favor, by creating artificial incentives for the banks to generate dangerously excessive exposures to what they officially perceived as “not-risky”, like the triple-A rated securities and “solid” sovereigns, while, equally dangerously, hindering the banks to attend to the credit needs of the “risky”, the small businesses and entrepreneurs. This the regulators did by means of their silly capital requirements for banks based on ex-ante perceived risks of default of borrowers. 

That is why I truly feel upset when, silencing my voice, you allow Ronnie Chan the space to argue that “The west is now in many respects too free”… and that perhaps the United States might be better off leaning more towards China’s ways, “The west is in danger of frittering away its freedom” November 15. 

What a baloney! What the west most needs is to free their banks from their current regulations. If the United Sates does collapse and therefore China does not collect it investments or can export more to it, I wonder where Mr. Ronnie Chan would prefer to be… in the United States or in China? I know for sure where I would like to be and I also hope those in the Financial Times are clear on that too.

November 14, 2011

Yes, ease the rules on small business loans, by eliminating the regulatory discrimination against these.

Sir, Patrick Jenkins and Brooke Masters on November 12report that Andrew Haldane, the Bank of England’s executive director of financial stability opines that “regulations that potentially constrain lending to small businesses should be eased [made less capital intensive] when the economy is suffering”. That is a marvelous opening for someone like me who has been for more than a decade clamoring to eliminate the regulatory discrimination against small businesses, though I would of course want that to happen at all times and not only when the economy is suffering. 

Andrew Haldane, with much honesty also says “At present [the risk-weights] are calibrated to the risk of a bank. In future they need to reflect returns to society”. Yes Mr. Haldane that is what they should have done all the time. 

What is really sad though is to read a senior regulatory specialist at a global bank saying “You can’t just change risk weightings at whim because what really matters is that risk is priced correctly”… this specialist, as most other specialists, has still not been able to figure out that you cannot price risk correctly when different risk-weights are imposed on different assets… and that is what have us all now drowning in the ocean of the ex-ante perceived as not at all risky assets.

November 13, 2011

Can we get us some good and courageous technocrats please!

Sir, Tony Barber writes “Enter the technocrats” November 12, and that could be good unless of course it is the failed technocrats who are entering… and frankly most of the European and American technocracy, in the area of finance, have failed miserably. 

Technocrats who never understood, and still fail to understand, that the risk-weights used for determining the capital requirements for banks that based on ex-ante perceived risk of default, were layered on top of the banker’ own risk-weights, which drove the banks to create dangerously high exposures to what is officially perceived as “not-risky”, are not worthy being called technocrats… no matter how revered they are in Brussels. 

At this time, when we all need the risk-takers to work for us, they are being choked by the lack of access to bank credit… just because these failed technocrats believe them to be risky. Come on, these were the regulators who believed sovereigns to be safe! Are we still supposed to blindly follow their courageous calls for entering their land of no-risks? 

These wimpy technocrats –bureaucrats, who demonstrated even less courage than many politicians, and who are in fact more responsible that most politicians for this crisis, do not seem to be the leaders we now need!

November 12, 2011

FT, I dare you!

FT, I dare you, following your motto “without fear and without favour”, to mark to market the bank regulators, like you so valiantly do with fallen Berlusconi in “Public Liability”, November 12. 

For instance, by allowing banks to hold zero or minimal capital against loans to their "safe" sovereigns, how many billions in lower interest did the regulators subsidize governments with? How much of the excessive sovereign debt is the direct result of such regulatory bias? How much bank lending to “risky” small businesses and entrepreneurs did not happen, only because these had to pay higher rates to make up for not being treated equally favorable?

In November 1998 in an Op-Ed titled “Burning the bridges in Europe” and that had to do with the fact there was no route out of the euro I wrote: “That the European countries will subordinate their political desires to the whims of a common Central Bank that may be theirs but really isn’t, is not a certainty. Exchange rates, while not perfect, are escape valves. By eliminating this valve, European countries must make their economic adjustments in real terms. This makes these adjustments much more explosive.” 

That Op-Ed clearly shows that I predicted what is now happening, but, what I was not aware of at that time, because I am neither a banker nor a regulator, was that the bank regulators were going to impose such a sick and really communistic capital controls in favor of their governments. Shame on them!

November 10, 2011

The rawest deal women entrepreneurs get in access to bank loans has nothing to do with their gender

Sir, Noreena Hertz writes that “Women are getting a raw deal in business and in finance” November 10, and bases that opinion on a study about the differences between women and men in terms of access to bank loans. She holds that if there was to be less discrimination more women entrepreneurs would be able to help out the economy, and she also makes reference to the possible legal consequences for the lenders.

She might be right, but, whatever discrimination women entrepreneurs are subject to because of their gender, pales in comparison to the odious arbitrary regulatory discrimination they are subject to because they are officially perceived as “risky”, and therefore the banks are forced to hold many times more capital when lending to them than what they are required to have when putting their money in triple-A rated instruments or sovereigns.

Since the “risky” are already discriminated against by banks in terms of interest rates, amounts, maturities and much other, the above amounts to layer a discrimination on top of a discrimination… something akin to asking the banks to hold more capital when lending to women.

If Noreena Hertz really wants to help she should first aim at the regulatory discrimination and once that idiocy dis taken care of, then she might perhaps request banks to be required to have somewhat less capital when lending to women, to compensate for the remaining discrimination.

November 09, 2011

But the misalignments turned monstrously large only because they were financed.

Sir, Martin Wolf in “thinking through the unthinkable” November 9, quotes Thomas Mayer of Deutsche Bank saying “below the surface of the euro area´s public debt and banking crisis lies a balance of payments crisis caused by a misalignment of internal real exchange rates”.

Yes, the misalignment of the real exchange rates within the eurozone were always in the cards, but the main reason for why they could grow so out of proportion was the fact that it could be financed… and the foremost cause of that were the truly stupid regulations which allowed the banks to finance European sovereigns against little or no capital at all.

I would presume Martin Wolf has many friends among regulators, while I have none, but nonetheless he should have used his column long ago to ask… is it rational to allow banks to finance for instance Italy and Greece, or any sovereign, against basically no capital at all? Had he and his colleagues done that, then perhaps Europe would have had a better chance to nip the current crisis in the bud.

I would be scared too by Michel Barnier…and by Sir Mervin King.

Sir, Alex Barker in “Barnier vs the Brits” November 9, writes about the fears of Sir Mervin King in that Brussels reforms will reshape a vital British industry, banking, to the benefit of eurozone rivals. Would that not be a case of plain vulgar under-the-table protectionism?

I do not know much about the competitive aspects of UK banks but, I would indeed be frightened if the banks of my country were to be even partially supervised by someone who when going to Washington D.C. presented in a brochure, as a success story of his office: “A French citizen complained about discriminatory entry fees for tourists to Romanian monasteries. The ticket price for non-Romanians was twice as high as that for Romanian citizens. As this policy was contrary to EU principles, the Romanian SOLVIT centre persuaded the church authorities to establish non-discriminatory entry fees for the monasteries. Solved within 9 weeks.” http://ec.europa.eu/solvit/problems-solved/discrimination/index_en.htm

And, if an owner of a small business or as an entrepreneur, classified as “risky” by the regulators, and in need or want of bank credit, I would also be scared witless by someone who even after the world has gotten itself into such enormous difficulties by the excessive bank exposures to what was ex-ante officially deemed as absolutely not-risky, during a conference in Washington, insisted on that his responsibility as a regulator is simply to avoid excessive risk-taking… but, come to think about it… so does also UK´s Sir Mervin King opine. Help!

November 05, 2011

In the name of Europe, America and the Western World, you of the Basel Committee go!

Yes, you wrote to Berlusconi “In the name of God and Italy go!” November 5 and I do not object to even one comma.

But, in the same vein, I would tell all bank regulators even loosely associated with the Basel Committee “In the name of Europe, America and the Western World go! Their treacherous risk avoidance gospel they preach to our banks, if allowed to continue, is going to take Europe, America and the Western World down.

November 02, 2011

And what about the long overdue challenging of the idols of global bank regulations?

Sir, when reading Rowan Williams, the Archbishop of Canterbury’ “Time for us to challenge the idols of high finance” November 2, I cannot but regret he did not include the need to also challenge the idols of global bank regulations. 

These regulators, more than anyone, because of their capital requirements based on ex-ante perceived risk of default, are the most to blame for a world that is sinking dangerously fast, in the overexposure to what was ex-ante perceived as not risky, like AAA rated securities, Greece and many more sovereigns; and the underexposure to those perceived as risky, the small businesses and entrepreneurs. 

If instead of analyzing the pro and cons of a financial transaction cost they had analyzed what those regulations mean to the downtrodden “risky”, in terms of additional burdens, and in terms of gifts to the already favored “not-risky”, they might have understood the real inequalities that are present in the banking system and prioritized their petitions better.

Risk-avoiders can huff and puff but they depend on risk-takers.

Sir, Martin Wolf’s “Creditors can huff and puff but they depend on debtors” November 2, is a great expose on the Janus-faced realities of deficits and surpluses, and also of the too-much-lending and the too much borrowings. 

I just wish Mr. Wolf, and so many with him, could get to understand that precisely the same relation exists between safety-and risk-taking. If the world does not take risks it will not be safe. On the contrary by interfering with their risk-weights based on what they perceived as not-risky they pushed the world into one of the greatest economic crisis ever. 

There is something fundamentally wrong when, for instance a UK bank, is required to have 8 percent in capital when lending to a UK small businesses or entrepreneur, but is (or at least was) allowed to have only 1.6 percent when lending to a sovereign rated like Greece was, which has absolutely nothing to do with the credit rating of Greece being correct or not. 

It really amazes me that Mr. Wolf does not see that risk-avoiders can huff and puff but they depend on risk-takers.

October 31, 2011

More than how the credit ratings are determined, it is how these are used that is important.

Sir, Gene B. Phillips makes some very common sense comments on the proposals in Brussels concerning credit ratings and the credit rating agencies. “Don’t see rating agencies all as one” October 31. That said both Mr. Phillips and all those in Brussels fail completely to identify the most important changes that need to occur, with respect to how those ratings are used by the regulators.

The first is that regulators should concern themselves more with the fact that credit-ratings could be wrong, instead of betting it all, as they have done with the capital requirements based on perceived risk, on the human fallible credit risk raters being correct.

Second, the regulators should have no business using the credit ratings to play risk-managers for the world, by means of assigning the risk-weights that determine the effective capital requirement for banks. Instead they should concern themselves more with how the bankers act and react to the credit ratings.

If the regulators had done that, they would not have placed us in the hole we now are in.

October 29, 2011

Even in very shallow waters one finds regulatory arbitrage

Sir, Gillian Tett in “Baggy surf shorts, ´top freedom´ and the greater cover up” October 29, seems be confessing having engaged in regulatory arbitrage when admitting that she never wore bikini tops in the UK but rarely wore bikinis tops in France”. 

Since Gett, when reporting, seems to be quite happy in general with the rulings of the Basel Committee for Banking Supervision, and this even when those regulations have resulted in serious “malfunctioning”, I wonder whether she might be suggesting we could benefit from a Basel Committee on Beach Dress Code. 

Indeed, that could put some global order on this delicate issue? But also, and from a pure tourism competitiveness point of view, is it really fair that some beaches allow nudity and others do not? I know, I hear you loudly, it depends on the quality of the nudity, but still, could this not be an issue for WTO?

October 28, 2011

Mr. Obama. Does no one inform you about what is happening?

Sir, I read President Barack Obama’s “Now for a firewall to stop Europe’s crisis spreading” October 28, and it makes me wonder about who is supposed to inform the US President about what is happening, as obviously he is not. 

The financial fire started with the AAA rated securities backed with lousily awarded mortgages to the subprime sector, which had become too popular with the banks because, as these were officially perceived as not-risky, they could be purchased against only 1.6 percent in capital, which allowed therefore the banks to leverage their equity 60 times and more, something which of course must sound pure music for the ears of bonuses recipients. 

When that “not-risky” AAA was discovered to be very-risky, the banks had to immediately look for other officially “not-risky” and where they for instance found Greece, and swamped it with credits until Greece also drowned. 

And so now they are looking for new officially “not-risky” borrowers, who they can lend to without much scarce bank capital being required. Therefore, in the current fire, the flames are jumping from one officially-“not-risky” tree to another officially-“not-risky” tree and the last standing officially-“not-risky” tree will presumably be the US dollar and US public debt, but once the flames reaches there, it will also burn. 

The only way to start building a firewall, or to rebuild what has been burned already, is to allow banks to lend to the officially-“risky”, like those small businesses and entrepreneur s and which, as a class, have never ever been the cause of a systemic bank. Mr. President may I humbly remind you of that when the going gets risky, we need so urgently the risky risk-takers to get going.

October 26, 2011

Mario, for God’s sake, cut off the gas

Sir, Martin Wolf calls out “Be bold, Mario, put out that fire…” October 26. And I would call out “Mario, for God’s sake, first cut off the gas”. 

The capital requirements for banks based on perceived risk and the scarcity of bank capital is forcing banks out of anything that is becoming perceived as more risky and into what, for the time being, is still perceived as less risky. This is making the financing of the already perceived as risky so much more difficult while at the same tome creating the excessive exposures that will finally turn the last standing absolutely not-risky into the mother of all risks. Mario Draghi… or whoever… this gas that feeds the fire needs to be cut off, immediately.

On a side note since Martin Wolf writes “The capital to protect the European banking system from big defaults by important sovereigns simply does not exist” I cannot refrain from asking and whose fault is that? Could the regulators who allowed the banks to lend to sovereign against basically no bank capital have anything to do with that?

October 25, 2011

We do not need bold stability, we need bold risk-taking!

Sir, Barry Eichengreen and Raghuram Rajan in “Central banks need a bigger and bolder new mandate” October 25, write “Financial stability must become an explicit objective of central banks, along with price stability” and I just must ask… what is so bold about that? 

The authors also opine the world has been rethinking bank regulations to make economies more stable and that has clearly not been the case. Basel III like Basel II is built upon the pillar of capital requirements for banks that discriminate based on ex-ante perceived risk and it was precisely that which caused this crisis by means of giving the banks those fabulous incentives that led to the buildup of so dangerous excessive exposures to what was ex-ante perceived as not risky. 

No what we need is bold rethinking which starts by asking Central banks and bank regulators to dare to tell us what they believe the purpose of our banks is… since nowhere is that to be found. 

The Western World became what it is based a lot on the willingness of banks to take risks… and especially when the going gets to be risky as now and we need our risk-takers, like small businesses or entrepreneurs to get going, we cannot allow some nannies to turn our banks into veritable wimps in the name of some misunderstood quest for stability.

We are better off with free market vigilantes

Sir, George Soros plan to save the eurozone, October 25, includes for the banks “to take instructions from the ECB on behalf of governments” and “installing inspectors to control risks banks take for their own account”… so that “markets will be impressed”. 

Has Soros gone mad or is he just a communist? Are we supposed to be impressed by our banks being supervised by those who authorized these to leverage their equity more than 60 to 1 when lending to Greece… and now complain about the downgrading of the credit ratings of sovereign? 

Oh no, I think we are much better off with free market vigilantes.

PS. If you have not seen it, here´s a video that explains a fraction of the stupidity of our bank regulations, in an apolitical red and blue! http://bit.ly/mQIHoi

October 24, 2011

Is it not time for Euro II?

Sir, Wolfgang Münchau, in “How Europe is now leveraging for a catastrophe” correctly paints scenarios so horrendous we wish we all were just having a nightmare. 

What if we could wake up and find a Euro II, with all European governments, Germany included, having given their creditors exactly the same haircut, for instance 40 percent, and used the excessive hair-cut in some countries, to compensate for the insufficient haircut in others. 

Why not? The bank regulations that allowed European banks to lend to Greece against only 1.6 percent capital, an authorized leverage of 62 to 1, and which of course pushed to create Greece’s excessive debts, were not just a Greek idea but a shared European one. 

And if thereafter Europe helps to avoid a repeat… like for instance requiring bankers to put up exactly the same capital when lending to a European sovereign as it has to put up when lending to a European small business or entrepreneur… could we all not wake up, hurting a lot, but at least looking forward immediately to a better future?


PS. This was written before I knew of the Sovereign Debt Privilege that assigned all eurozone sovereigns a 0% risk weight even if they were taking on debt denominated in a currency that de facto was not their own domestic printable one. That was even crazier than Basel I or II.

October 22, 2011

Should Lord Turner have the right to throw the first stone?

Sir in your “Sustainable banks” October 22 you refer to a speech by Lord Adair Turner in which the chairman of the Financial Services Authority referred to the need for more transparency and less opaque pricing in banking. Right so, indeed… but is Lord Turner the right person to throw the first stone? 

The banks, when lending to those officially perceived as less-risky, like for instance Greece was perceived to be, were allowed to hold much less capital than when lending to those officially held as “risky”, like the unrated small businesses and entrepreneurs in the UK. 

How much in extra interest rates, or in less access to credit, have the small businesses and entrepreneurs have had to pay because of that? Fortunes! Has Lord Turner been transparent about that? 

Has Lord Turner been transparent about the fact that these misguided capital requirements, based on ex-ante perceived risks, are to blame for the current dangerous excessive exposures of banks to what was perceived ex-ante as not risky… and which might even have been turned into risky, precisely because of that regulatory nanny like anti-perceived-risk bias? 

PS. In case you need some reminders, here´s a video that explains a small part of the craziness of our bank regulations, in an apolitical red and blue! http://bit.ly/mQIHoi

October 21, 2011

Mr. Daniel Tarullo, first, stick to your area!

Sir, according to Robin Harding and Michael MacKenzie, in “Fed urged to weigh new moves to boost economy” October 21, Daniel Tarullo, whose “main area of focus is banking supervision and regulation rather than monetary policy” refers to that the US Federal Reserve “should consider large-scale purchases of mortgage backed securities if the economy does not improve”. 

As most of these securities have already seen their values adjusted in the market, I cannot see what good that would do… unless it is part of a huge plan of restructure all the underlying mortgages in accordance of their market value, not something totally senseless, but that would certainly require a major administrative effort and the consideration of moral hazard. 

Much easier it would be for Mr. Tarullo to concentrate on his area and push, for instance, for the immediate drastic reduction in capital requirements for banks, when lending to any business with total liabilities, for instance, below a level of 10 million dollars. That would be a good way to start alleviating the damages done to all small businesses and entrepreneurs by the fact that bank are allowed to lend to others perceived as not-risky, with much lower capital requirements. 

PS. In case you want more details, here´s a video that explains a small part of the craziness of our bank regulations, in an apolitical red and blue! http://bit.ly/mQIHoi

Hollywood would never have allowed Basel III after the Basel II magna flop

Sir, Kishore Mahbubani writes “Now we know that bankers produced no economic value. Instead they produced financial weapons of mass destruction that almost destroyed the world… European bankers… ignoring common sense… lent money to Athens on the assumption that Greece was as solvent as, say Germany”, “To become rich is great but to pay taxes is glorious”, October 21. 

That shows precisely what happens when the whole truth is not allowed to surface. It was the bank regulators who, when they allowed the banks to leverage differently their equity, by means of capital requirements based on ex-ante perceived risk, Basel II, which created what I have called the AAA-bomb… a truly massive weapon of mass destruction. 

It was those regulations which allowed banks to stock up on Greek sovereign debt against only 1.6 percent capital, a leverage of 62.5 times, while at the same time forcing banks to hold 8 percent when lending to small businesses or entrepreneurs, a leverage of 12.5 times, which gave the incentives to created the huge exposures to where all bank crisis occur, namely where the risk is ex-ante perceived as almost non-existent. It was those odiously distorting regulations that short-circuited the markets… and still keeps these from functioning. 

And because this is silenced, we allow the same producers of the failed Basel II, to produce Basel III, with only minor changes in the script. Friends, Hollywood would never allow such a thing. No, to be able to hold bank regulators accountable, that is what would be really glorious.

Even the most perfect monetary union would not withstand what attacked the Europe and the Euro

Sir, Steve Rattner holds with respect to Europe that “today’s crisis is structural… stemming from the euro’s flawed design. “Look to America for lessons in sharing currency” October 21.

The same week the euro was launched, in an Op-Ed, I predicted all the problems that could arise, with one notable exception. What I did not predict was the possibility of having bank regulators allowing the banks to leverage 62 times, at least, when lending to the European Sovereigns. And that my friends, is an attack that not even the most perfect monetary union could have defended itself against. 

To honestly recognize that is a must, in order for Europe to understand that it was not really the Euro or Europe which failed, to avoid the self-doubts, so as to be able to regain the confidence necessary to move the Euro and Europe forward.

October 19, 2011

The Basel bank reforms are just the continuation of a failure

Sir, Brooke Masters, while reporting “Countries fail to enact Basel bank reforms” October 19, writes: “Basel II is seen as having contributed to the 2008 banking crash by allowing banks to understate risk and hold too little capital against unexpected losses”. 

“Allowing banks to understate risk”? What is she talking about? If you read the risk-weights assigned by the regulators in the Basel II documentation you would find, for instance, a risk-weight of a mere 20 percent for a sovereign rated like Greece was during its build up of public debt, and which allowed banks to hold only 1.6 percent in capital when lending to Greece, and which therefore allowed the bank to leverage their capital 62 to 1 when lending to Greece. It was, without any doubt, the regulators who understated the risks! Don’t let them get away with that! 

It is also reported there that the “risk-based structure remains an essential tool of the stricter Basel III framework which includes higher capital requirements”. I do not want to be a party pooper but, let me remind you that the stricter and higher the basic capital requirements for banks are, the worse the dangerous distortions produced by the discriminating risk-weights. 

That some countries fail to enact the reforms is not that surprising, since what’s really incredible is that so many of these allow the same producers of the utterly failed Basel II to produce Basel III, while keeping the same script faults.

To stand a better chance of a sunlit future, we must pour sunlight on the truth.

Sir, Martin Wolf in “There is no sunlit future for the Euro” October 19, writes with respect to the banks holding Greek debt, “Fools who lent money, without asking questions, deserve to share in the pain.” That is undoubtedly true, but not focusing with the same impetus on the role of the regulations in building up Greece’s excessive debt, impedes the truth from coming out. The fact was that during the whole period of Greek debt buildup, banks were authorized, by Basel II, to leverage their capital 62.5 times to 1 when lending to Greece. That meant that banks were able to make immensely higher risk-adjusted returns on equity when lending to Greece as compared for instance when lending to a European entrepreneur; and that mean that Greece was required to pay lower interest than would have been the case without that regulatory interference with the market. 

Why do I after hundreds of ignored letters to the Editor of FT about this, insist on sending them. Simply because I know that the basic level of capital requirements for banks had nothing to do with this crisis, it was the specific capital requirements after the risk-weights that caused it. You might find a solution to a problem without knowing its real cause, but, it is so much easier when that real cause is recognized. So let us start by pouring sunlight on that! 

Wolf makes sensible suggestions for the increase by governments of the capital of banks. But, lowering the capital requirements for banks, especially when these are very high given the current scarcity of bank equity… could provide the same results. I am indeed curious as to why Wolf, who supports increased fiscal spending, even in light of huge public debt and enormous deficits, does not support allowing the banks to do their lending job easier.

October 12, 2011

A market adjusted very risky sovereign debt could be less risky than an AAA-rated sovereign debt.

Sir, Patrick Jenkins, Ralph Atkins, Peter Spiegel and Alex Barker in their “Europe’s banks face 9% capital threshold” write that according to the European Banking Authority’s board of supervisors, “banks should be made to raise their core tier one capital ratios – the key measure of financial strength even after absorbing write-downs on the value of their sovereign debt holdings.” 

Here are two questions: Should the credit rating be the same for a debt acquired at its nominal value of 100% than the credit rating of that same debt for someone who acquired it after for instance it has been discounted in the market for the credit risk to be worth only 50 percent? Or, could not a BBB rated debt acquired at 50 percent be safer than an AAA rated debt valued at 100 percent? 

In answering them, you will understand why the bank regulators have placed us in a hole and why they only keep digging us deeper in it. 

You can have the regulators measuring the risks, not recommended, or you can have the market doing that, but, what you cannot do, under no circumstances is to use and add those both measures simultaneously, and expect to obtain something reasonable. 

October 10, 2011

Stefan Ingves, defends a bank leverage of 33 times to 1. Why?

Brooke Master reported on October 10 that Stefan Ingves, the new chairman of the Basel Committee for Banking Supervision said: “It all boils down to capital ‘the ultimate brake’ If you don’t have enough simple common equity you will run into problems… If one looks at banking systems running into troubles, you almost always find ex-post facto that there was too much leverage”. On that we all agree. 

But then, ipso facto, Ingves says, “I find it hard to argue that you would need to go above leverage of 33 times”… and I, as a tax-payer, as one of the ultimate picker-uppers, or at least as a grandfather to one, must ask, why on earth that high? Why not 12 to 1 for example? 

If Stefan Ingves wants to defend a 33 times bank leverage he is of course in his right, but the least we can do is to ask him to explain the purpose of that. Is it so that banks can help us to create jobs? In that case would it then not be better to reserve that bank lending power for the small businesses or entrepreneurs, instead of wasting it on those perceived ex-ante as having no-risk and who, almost by definition, must be the largest suppliers of those dangerous “unexpected losses” he speaks of?

Or could it just be that the whole purpose of our banking system has been reduced to have banks making profits? If it is so, how vulgar of the regulators.

October 09, 2011

Jean Claude Trichet (and Mario Draghi) should not to be condoned by FT

Sir, you hold that “Trichet leaves Europe in his debt” October 8, as the responsibility for “reckless bank lending”, “rests largely with national politicians and policymakers”, and I must most firmly disagree. 

Jean Claude Trichet, as the President of the European Central Bank, must have been much more aware than the politicians of the existence of the outrageous bank regulations which allowed European banks to leverage 62.5 to 1 and more their equity when lending to almost any sovereign in Europe or investing in triple A rated securities… and he should be held accountable for that, something which equally applies to the incoming president of ECB Mario Draghi. 

If you harbor any doubts about what I am saying, just go back to the hundreds of articles between 2008 and 2010 where your own reporters spoke of the banks having reasonable leverage ratios, completely fooled by the zero and 20 percent risk-weights applied by regulators and that was hiding humongous risky bank exposures.

September 17, 2011

And what about the elite of rogue regulators?

November 1999 in an Op-Ed in the Daily Journal of Caracas I wrote “The possible Big Bang that scares me the most is the one that could happen the day those genius bank regulators in Basel, playing Gods, manage to introduce a systemic error in the financial system, which will cause its collapse”… and so they did! 

The bank regulators decided that banks were to be allowed to leverage their capital much more when earning the risk-adjusted interest rates from those perceived as “not-risky” than when earning those same interests lending to those perceived as “risky”, which caused trillions of dollars in losses from investments in AAA rated securities collateralized with lousy awarded mortgages, and the trillions of dollars in excessive bank exposure to the “not-risky” sovereigns that are blowing up all around us. 

John Gapper writes about “A revolt against the risks of elite international finance” September 17, but, among the international elite, he fails to include the rogue regulators and who, by keeping their risk-weighting in Basel III, arrogantly keep on playing the role of risk managers for the world.

September 14, 2011

Mr. Regulator, tear down this Basel wall

Sir, John Kay writes “Without ringfencing it will soon be a case of ‘here we go again’, September 14. May I suggest that instead of thinking about ringfencing, we should be thinking more about tearing down walls. 

Basel bank regulations built a wall that, with its capital requirements, arbitrarily discriminates in favor of what is dangerously perceived as “not-risky” and against what wimpy regulators consider the dangerous “risky”. 

This wall drove the world to a crisis, by means of generating excessive bank exposures to what was ex-ante perceived as “not-risky”, and is stopping the world from getting out of it, by making it harder to enlist the help of the “risky”, the small businesses and entrepreneurs. 

Therefore, for the benefit of the future, Mr. Regulator, tear down this Basel wall!

September 12, 2011

Basel regulations should be anathema to “the Land of the Free and the Home of the Brave”

Sir Tom Braithwaite and Patrick Jenkins report that JPMorgan chief says bank rules are “anti-American”, September 12. Jamie Dimon is more right than he probably knows, and, also, the anti-Americanism of Basel regulations, started long before Basel III. Just consider the following: 

By allowing banks to leverage more their capital when earning the risk-adjusted-interest-rate from those perceived as “not-risky” than when earning the same rate from those perceived as “risky”, regulators introduced a silly and unproductive risk-adverseness that is not compatible with “the Home of the Brave” 

Allowing banks to leverage immensely more their capital when lending to sovereigns like the USA government, than when lending to American small businesses and entrepreneurs, is communism, and absolutely not compatible with “the Land of the Free”

The Vickers Report, like the Basel regulations, would benefit from defining the purpose of banks.

The current crisis was caused, almost entirely, by regulators arbitrarily setting risk-weights which allowed banks to lend or invest in sovereigns and what was triple-A rated with truly minuscule capital, 1.6 percent or less. As the Vickers Report keeps the notion of capital requirements based on risk-weighted assets, it does not protect against what it needs to protect.

Here is a question that I dare John Vickers and his colleagues to answer. Why should banks be allowed to leverage their capital more when earning their risk-adjusted-interest-rates from what ex-ante is perceived as the “not-risky”, than when earning these from the “risky”? Does that not mean that the “risky”, like the job creating small business or entrepreneurs, will then need to pay the banks higher interest rates than would otherwise have been the case without regulatory intervention? Or vice-versa that the “not-risky” will benefit from lower interest rates than the market rates? 

It is high time to stop thinking in terms of “buttressing the banks” and start thinking in terms of “buttressing the role of banks in the economy” For instance, is not the risk of an economy without jobs for our youth much riskier than having some banks failing?

September 09, 2011

Getting rid of the regulatory discrimination against the “risky”, that’s what the world most needs to boost growth.

Sir, it is sad indeed when in Timothy Geithner’s “What the world must do to boost growth”, September 9, more than 3 years after the crisis started, we still do not read a word about the importance of eliminating the arbitrary regulatory discrimination against bank lending to job creating small businesses and entrepreneurs, and which is all based on the utterly silly notion that these borrowers are more risky.

September 03, 2011

But how can we sue the devil who tempted?

Sir in “Suing the banks”, September 3, you write “Those who made the mortgage mess should be accountable”. Indeed, and so I ask, where can we sue the guiltiest of all, the bank regulators? 

The regulators, by permitting the banks having minuscule capital, only 1.6 percent, when lending or investing in what was ex-ante perceived as “not-risky” and had managed to hustle up a triple-A rating, offered the apple that tempted the market and doomed us to this mess. Without it there would never ever have been such a demand for those lousy mortgages.